Deck score and investor replies: what the data can and can't tell you
It is the chart everyone wants from us. Deck score on one axis, reply rate on the other, a line going up and to the right. It would sell a lot of deck scores.
We tried to make it. We are not going to publish it, at least not yet. This guide explains why, what we can say instead, and what that means for the deck you are about to send.
Two numbers we trust
We have two solid datasets, both from April 16 to October 6, 2026.
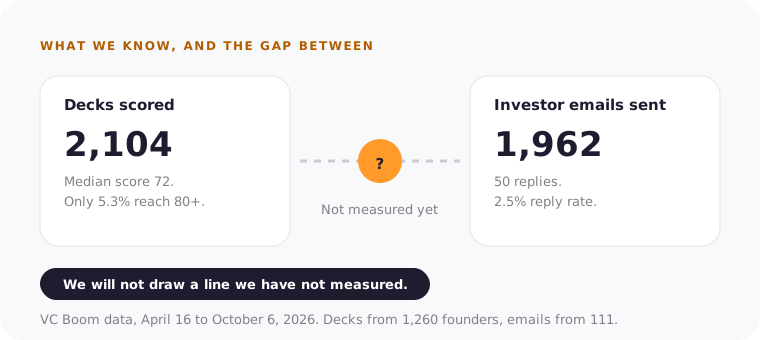
2,104 decks scored. 1,962 investor emails sent. The line between them is not measured yet.
Decks. 2,104 decks scored from 1,260 founders. The median score is 72. Only 5.3% score 80 or higher.
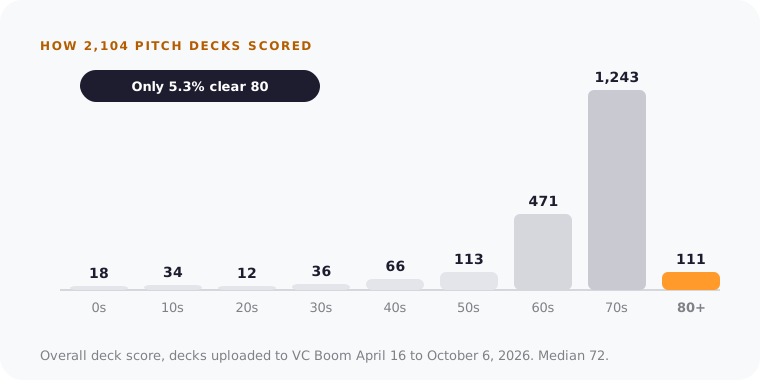
Most decks land in the 70s. Very few clear 80.
Emails. 1,962 investor emails sent by 111 founders. 50 got a reply. That is a 2.5% reply rate.
Why we have not linked them
On paper it is a simple join: take each sent email, look up the score of the deck behind it, group by score band, compute a reply rate per band. Here is why we do not trust the result.
There are only 50 replies. Split 50 replies across four or five score bands and some bands have a handful. One founder getting two lucky replies would swing a band by several points.
One founder sent 834 of the 1,962 emails. That is 43% of everything we have. Whatever score their deck had, that band's "reply rate" would mostly be one person's reply rate. We learned this the hard way when an early cut of our data made Wednesday look like the best day to send. It was that founder's calendar. Without them, Tuesday and Wednesday came out at 2.9% and 3.1%, and we stopped claiming a best day.
Most founders who score a deck never send. 319 founders drafted an investor email, and only 111 sent one. Founders who send may differ in many ways from those who do not: stage, sector, network, urgency. Any score-to-reply line would mix all of that in.
Decks change between sends. Founders rescore and fix their decks. Which score do you attach to an email: the one at upload, or the one on the day it was sent?
None of this is impossible to solve. It needs more replies and more founders. When the sample is big enough to survive removing the largest sender, we will publish the chart, whatever it shows.
What it would take to draw the line
So you know what we are waiting for, here is the bar we have set ourselves before publishing a score-to-reply chart:
- Enough replies per band that a single founder's luck cannot move a band by more than a point or two.
- The chart must survive removing the largest sender. If the pattern only exists with them in it, it is their pattern, not a finding.
- One score per email, taken from the deck version that was live on the day the email was sent.
- A caveat on selection, in the chart itself, not in a footnote.
We would rather publish nothing than publish a line that falls apart when one founder is removed. Until then, any "decks above X get Y% replies" claim you see, from us or anyone else, deserves a question: how many replies, from how many founders?
What the data does show
Two findings in our outreach data hold up well enough to share, with their caveats.
Smaller batches are associated with higher reply rates.
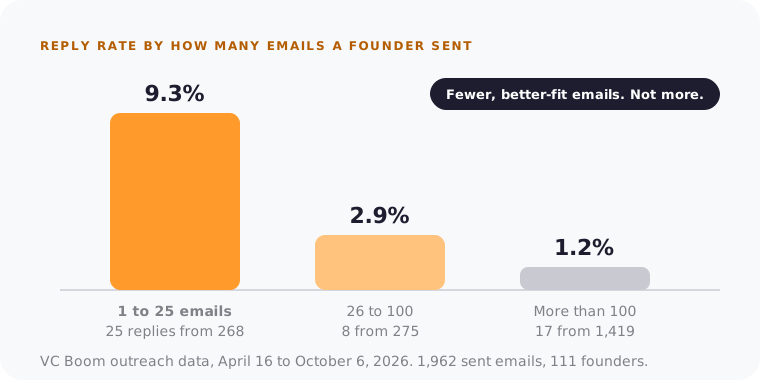
Founders who sent 25 emails or fewer: 9.3%. More than 100: 1.2%.
This is an association, not a cause. Founders with a stronger company or a clearer fit may simply need fewer sends. It may well be that those founders also have better decks. We just cannot separate the two yet.
Verified addresses got more replies. 2.7% against 1.7% for catch-all addresses, and the gap holds without the largest sender (3.0% against 2.0%). Our guide on reaching the right partner covers how to check yours.
The case for fixing the deck anyway
Without the chart, why bother with your score before sending? Not because a number predicts replies. Because of what the deck does to everything around it.
A clear deck makes a clear email. The first two lines of a good cold email are what you do and your strongest proof. If your deck has not worked those out, your email will not either. When we read the 50 emails that got replies, the proof line stood out: an approval, a patent, signed revenue, something an investor can check.
The weak spots are predictable. Traction is the lowest-scoring dimension, averaging 60.0 out of 100, with 44.2% of decks below 60 on it. Business model (65.6) and the ask (66.1) follow. Those are the same things an investor's first questions will be about. Fixing them before the first meeting means the meeting is about your business, not about what your slide meant.
The investor clicks through. If your email works, the next thing they open is the deck. That is where a confusing traction slide or a vague ask costs you the meeting.
What a deck in the 70s should do
Most decks are in the 70s, which the scorer calls strong: one or two fixable gaps from a yes. You are not far off. Here is what we would do:
- Find the lowest dimension. Usually traction, business model or the ask.
- Fix that one slide. Dated, real numbers on traction. Current unit economics, even if early, on the model. Amount, instrument and milestones on the ask.
- Rescore once. If it moved, stop polishing.
- Send to a short list. About 25 investors who fit your stage, sector and check size. Our guide on building your first investor list walks through it.
A deck below 60 is different. That usually means a missing piece, not a weak slide: no clear problem, no evidence anyone wants it yet, no specific ask. Fix the fundamentals before you spend your list. Our rubric guide explains what each dimension looks for.
What to do this week
- Score your deck and write down the overall score and the lowest dimension.
- If you are below 60, do not send yet. Fix the fundamentals.
- If you are 60 to 79, fix the lowest slide, rescore once, then send.
- If you are 80 or above, stop editing. Your time is better spent on the list and the email.
- Track replies, not opens. Opens are tracked by a pixel that Apple Mail and Gmail proxies distort, so we do not use them, and you should not either.
Score it, then send it
VC Boom scores your deck across seven dimensions and tells you which slide to fix first. Then it ranks investors who fit, from the 47,874 we track, and drafts the first email.
Score your deck for free and see your weakest dimension.